


Receiving a denial letter from your insurance company feels like a final verdict, but it’s actually just the first step in a negotiation. Many homeowners assume a rejection means they’re stuck paying for repairs out of pocket, yet learning how to appeal a denied roof insurance claim can change everything. You’ve paid your premiums faithfully for years. When a severe storm leaves your roof compromised, being told “no” feels like a betrayal of that trust. We understand the financial stress and the fear of being lowballed by a major carrier while your Tulsa home sits vulnerable to the next Oklahoma rain.
You don’t have to handle this bureaucracy alone or accept an unfair decision. This guide will show you the exact steps to overturn a denial so you can secure the full coverage your property requires in 2026. We’ll provide a clear checklist for the appeal process, explain how to gather the technical documentation adjusters demand, and show you how local expertise can help get your roof replacement approved. Your “no” can become a “yes” with the right approach and a bit of neighborhood support.
Key Takeaways
- Understand the specific language in your denial letter to distinguish between normal wear and tear and valid storm damage.
- Discover how to appeal a denied roof insurance claim by gathering professional-grade technical evidence that adjusters cannot easily dismiss.
- Learn the proper way to draft a formal Notice of Dispute and request a second inspection with a senior adjuster to ensure a fair review.
- Avoid common mistakes like repairing damage too early or waiting too long, both of which can lead to a permanent claim denial.
- See how local Tulsa experts handle the administrative burden of insurance claims to help you secure a full roof replacement.
Why Was My Roof Claim Denied? Decoding Your Letter
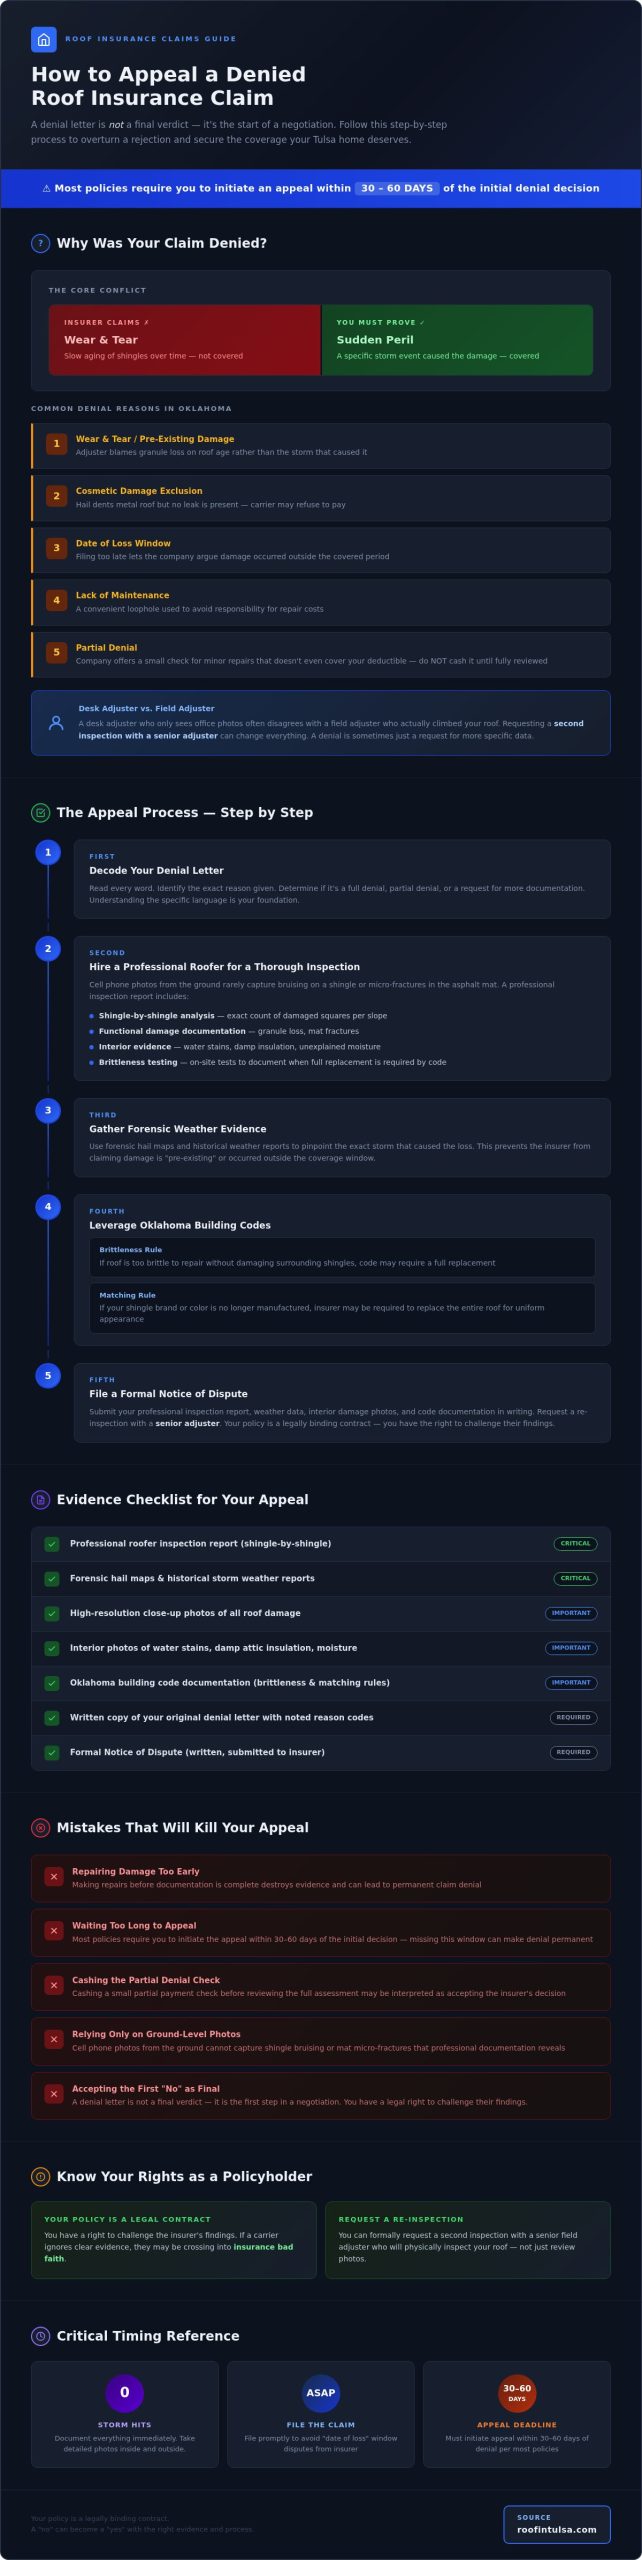
Opening your insurance denial letter can feel like a punch to the gut. You see the word “denied” and assume the case is closed. However, understanding why the carrier rejected your claim is the first step in learning how to appeal a denied roof insurance claim. In Tulsa, the most frequent conflict arises from the distinction between “wear and tear” and “sudden peril.” Insurance is designed to cover sudden events, like a 2026 hailstorm, rather than the slow aging of shingles. If an adjuster can blame the damage on the age of your roof rather than a specific storm, they’ll likely do so.
Pay close attention to “partial denials” in your paperwork. This occurs when a company agrees to pay for minor repairs but refuses a full replacement. You might see a check for a few hundred dollars that doesn’t even cover your deductible. Don’t cash this check until you’ve reviewed the full assessment. Adjusters also use the “pre-existing damage” trap to avoid high cost replacements. They might point to minor granule loss as evidence that your roof was already failing before the storm hit. You must act quickly. Most policies require you to initiate the appeal process within 30 to 60 days of the initial decision.
Common Denial Reasons in Oklahoma
Oklahoma policies often include “cosmetic damage exclusions.” This means if hail dents your metal roof but doesn’t cause a leak, the carrier may refuse to pay. Another hurdle is the “date of loss” window. If you wait too long after a storm to file, the company will argue the damage happened outside the covered period. They may also cite a “lack of maintenance” as a convenient loophole to avoid responsibility. We help homeowners identify these loopholes so they can provide the specific proof needed to close them.
Understanding the ‘Right to Appeal’
Your insurance policy is a legally binding contract. You have a right to challenge their findings. Sometimes, a denial is simply a request for more specific data. A desk adjuster, who only sees photos from an office, often disagrees with a field adjuster who actually climbed your roof. If a carrier ignores clear evidence, they might be crossing into insurance bad faith. Knowing how to appeal a denied roof insurance claim starts with realizing that the first answer isn’t always final. You deserve a fair evaluation based on the actual condition of your Tulsa home.
Step 1: Gathering Technical Evidence for Your Appeal
Cell phone photos from the ground rarely capture the bruising on a shingle or the micro-fractures in the asphalt mat. To understand how to appeal a denied roof insurance claim, you must realize that insurance carriers prioritize high-resolution, technical data over casual snapshots. They want to see what is happening underneath the surface. This is where a professional roofing contractor becomes your most valuable ally. They can identify hidden storm damage that an untrained eye or a rushed adjuster might overlook during a 2026 inspection.
Beyond the roof itself, you need to prove exactly when the damage occurred. Tulsa weather is notoriously volatile. We use forensic hail maps and historical weather reports to pinpoint the specific storm that caused the loss. This data prevents the insurance company from claiming the damage is “pre-existing” or occurred outside the coverage window. Don’t forget to look inside your home as well. Water stains on the ceiling, damp insulation in the attic, or unexplained moisture are all critical pieces of evidence that link exterior damage to interior failure.
The Roofer’s Inspection Report
A professional inspection report provides a comprehensive, shingle-by-shingle analysis of structural integrity that far exceeds the brief, generalized summary typically provided by an insurance adjuster. Our reports include detailed shingle counts, documenting the exact number of damaged squares across every slope of your home. We look for functional damage, such as granule loss and mat fractures, which often lead to leaks years before they are visible from the street. This level of detail makes it much harder for a carrier to dismiss your claim.
Leveraging Local Tulsa Building Codes
Oklahoma building codes are a powerful tool in your appeal. For example, if a roof is too brittle to be repaired without damaging surrounding shingles, the code may require a full replacement. We perform “brittleness tests” on-site to document this reality for the adjuster. Additionally, the “Matching Rule” is vital. If your specific shingle brand or color is no longer manufactured, the insurer may be required to replace the entire roof to ensure a uniform appearance. These local regulations often turn a denied patch job into a fully covered replacement. If you’re feeling overwhelmed by the paperwork, scheduling a professional roof inspection is the best way to build your case with facts.
Step 2: The Formal Appeal and Re-Inspection Process
Once you’ve gathered your technical evidence, it’s time to move from the collection phase to the action phase. Understanding how to appeal a denied roof insurance claim requires a formal, methodical approach. You can’t just call your agent and hope for a change of heart; you need a documented paper trail. This begins with a “Notice of Dispute.” This is a formal letter stating that you disagree with the insurer’s findings and intend to seek a re-evaluation of your Tulsa property.
When you request a second look, ask specifically for a supervisor or a “senior adjuster.” These professionals often have more authority to overturn previous decisions than the initial field adjuster. It’s a common step in how to appeal a denied roof insurance claim because it brings a more experienced set of eyes to the situation. A senior adjuster is often more familiar with complex Oklahoma storm damage patterns and may be more willing to listen to professional counter-arguments.
Filing Your Official Appeal Letter
Your letter should be concise and professional. Include your policy number, the specific claim number, and a bulleted list of why you believe the initial assessment was incorrect. Attach your contractor’s detailed estimate and the Ultimate Homeowner Checklist to show you’ve done your homework. In 2026, sending this via certified mail is non-negotiable. It provides legal proof that the company received your dispute, which prevents them from claiming they never saw your request or that you missed a deadline.
The Re-Inspection Meeting
Never let an insurance adjuster onto your roof alone during a re-inspection. Your roofing contractor should be present to walk the slopes with them. Your roofer will use chalk to mark specific areas of damage, such as hail bruises or wind-lifted shingles, that were missed during the first visit. This creates a collaborative yet firm environment where your interests are represented by a professional. If the adjuster offers a “partial” approval, like replacing only one slope, don’t feel pressured to sign immediately. Discuss the offer with your contractor to see if it truly restores your home to its pre-storm condition.
If you and the insurer still can’t agree on the value of the damage after a re-inspection, look for the “Appraisal Clause” in your policy. This is a powerful tool that triggers an independent valuation process. You hire an appraiser, they hire an appraiser, and these two select a neutral “umpire.” Their decision is usually binding. It’s a reliable way to break a stalemate without the need for a long, expensive court battle.
Avoiding Common Mistakes That Kill an Appeal
While learning how to appeal a denied roof insurance claim, it’s easy to let frustration lead to costly mistakes. One of the most damaging errors is “cleaning up” or performing permanent repairs before the senior adjuster arrives for the re-inspection. If the physical evidence of the storm is gone, the carrier has no reason to overturn their initial decision. You must preserve the scene exactly as it was after the storm. Similarly, avoid the temptation to wait until next year to address a denial. Insurance companies track Tulsa weather patterns closely. If you delay, they will argue that subsequent storms or simple aging caused the issues, which often leads to a permanent denial of coverage.
Many homeowners worry that cashing an initial settlement check ends their right to appeal. Usually, that first check represents the “undisputed” amount the company agrees they owe you. You can typically cash it to begin necessary work, but you must be extremely careful. Never sign any document that includes language like “full and final release” or “settlement in full” without professional advice. Doing so could legally close your claim forever. Additionally, watch your terminology. Using the wrong words, such as calling storm damage “old age” or “general leaking,” gives the carrier a convenient excuse to categorize the loss as maintenance rather than a covered peril.
The Risk of Temporary Patches
You have a legal responsibility to prevent further damage to your home, such as interior leaks. If you need an emergency roof repair tulsa, keep it limited to temporary mitigation like tarping or minor sealing. Take high-resolution photos before and after the patch is applied to show the original damage. Save every receipt for materials and labor, as these costs are often reimbursable as part of your claim. Be wary of “storm chasers” who knock on your door offering to handle your appeal. These out-of-state companies often disappear once the check is cut, leaving you with no local support if the roof fails later.
Managing Your Expectations
The appeal process is a marathon, not a sprint. It typically takes between 30 and 90 days to reach a final resolution. If you hit a wall, the Oklahoma Department of Insurance (OID) serves as a helpful last resort for filing consumer complaints. However, if the carrier remains stubborn despite clear evidence, it may be time to transition from a contractor-led appeal to a Public Adjuster or a specialized attorney. Most claims are settled through professional documentation and persistence, avoiding the need for expensive legal action. If you need a partner to help navigate this process, contact Rescue Roofing Tulsa for a professional consultation.
How Rescue Roofing Tulsa Supports Your Claim Appeal
Navigating the complex world of insurance paperwork is exhausting, especially after a storm has already disrupted your life. We developed our “Insurance First” approach because we know that homeowners shouldn’t have to be experts in policy language to get a fair result. Our team speaks the same technical language as adjusters. We don’t just tell them a roof is damaged; we show them using the high-resolution evidence and forensic data they require. This bridges the gap between a denied claim and a successful replacement, ensuring your Tulsa home receives the protection it deserves in 2026.
Our local roots give us a distinct advantage. We understand the specific tactics common carriers use in Oklahoma and the exact building codes that can turn a “no” into a “yes.” We take the administrative burden off your shoulders by handling the re-inspection meetings and technical discussions directly. This zero-stress process means you can focus on your family while we focus on the shingle counts and mat fracture documentation. We are your neighbors, and we are committed to seeing our community restored one roof at a time.
Why Experience Matters in an Appeal
We have a proven history of successfully overturning denials for homeowners across the region. Having an experienced residential roofing contractor by your side is vital because we understand the nuances of policy limits and coverage triggers. We provide comprehensive estimates for roof repairs or full replacements that carriers respect. These reports are built on industry-standard software that adjusters recognize, which adds immediate credibility to your dispute. When you know how to appeal a denied roof insurance claim with professional backing, your chances of a favorable outcome increase significantly.
Start Your Appeal Today
A denial letter is a hurdle, not a dead end. It is often just an invitation to provide better data. Don’t let a major carrier’s initial decision compromise the safety of your property or your financial peace of mind. We are here to help you gather the facts and present a case that cannot be ignored. Our team is ready to stand with you through every step of the re-inspection and negotiation process. Learning how to appeal a denied roof insurance claim starts with a single phone call to a team that understands the Tulsa landscape. Contact Rescue Roofing Tulsa for a Free Inspection and let us help you get the coverage you’ve already paid for.
Secure Your Home’s Future Today
A denial letter shouldn’t be the final word on your roof’s integrity. By decoding the insurance company’s terminology and gathering professional-grade technical evidence, you can present a case that demands a second look. Success depends on acting quickly within the first 60 days and ensuring a trusted local expert represents your interests during the re-inspection meeting. Whether it’s identifying hidden hail bruising or leveraging Oklahoma building codes, the right documentation turns a rejection into a restoration.
Understanding how to appeal a denied roof insurance claim is about persistence and precision. You don’t have to face the bureaucracy alone. At Rescue Roofing Tulsa, we are a locally owned team offering 24/7 emergency storm response and expert insurance claim assistance. We understand the specific weather challenges of 2026 and the exact data adjusters require to approve full replacements. We take the stress out of the process so you can focus on what matters most.
Take the first step toward overturning your denial. Get a Free Professional Inspection to Support Your Appeal and let us help you protect your biggest investment. Your home deserves a roof that lasts, and we’re here to make sure you get the coverage you’ve already earned.
Frequently Asked Questions
Can I appeal a denied roof claim myself, or do I need a lawyer?
You can certainly initiate the process yourself, though most Tulsa homeowners find success by partnering with a roofing contractor first. A lawyer is generally only necessary if the carrier acts in bad faith or refuses to follow the policy terms. Most technical disputes are settled through better documentation and re-inspections. We specialize in providing the high-resolution evidence that helps resolve these disagreements without the need for expensive legal fees.
How long do I have to appeal a roof insurance claim denial in Oklahoma?
In 2026, you should act within 30 to 60 days of receiving your denial letter to keep the process moving. While Oklahoma law provides a longer window for filing a lawsuit, insurance companies have internal deadlines for re-opening a file. Waiting too long allows the carrier to argue that new storms caused the damage. Prompt action is the most effective way to learn how to appeal a denied roof insurance claim successfully.
What is an ‘Appraisal Clause’ and when should I use it?
The Appraisal Clause is a dispute resolution tool found in most Oklahoma policies. You should use it when you and the insurer agree that damage is covered but disagree on the total cost of the repairs. Both parties hire independent appraisers who then select a neutral umpire. This process is often faster than a lawsuit. It provides a binding decision on the dollar amount needed to restore your home to its pre-storm condition.
Will my insurance rates go up if I appeal a denied claim?
Appealing a denial should not cause your individual rates to increase. Oklahoma is a high-risk storm state, and premiums are generally adjusted based on regional weather patterns rather than a single claim for an “Act of God.” Your rates are more likely to be affected by the overall number of claims in your zip code. Standing up for your right to a fair settlement is a standard part of property ownership in Tulsa.
What if the insurance company says my roof is just ‘old’?
Insurers often cite “wear and tear” to avoid paying for storm damage. If your carrier claims your roof is just old, we counter that with forensic evidence of functional damage. We look for specific hail bruises or wind-lifted shingles that occurred during a documented 2026 storm. Age doesn’t disqualify you from coverage if a covered peril caused the actual failure. We help you prove the storm was the primary cause of the loss.
Do I have to pay for a second inspection during an appeal?
You typically don’t have to pay for a second inspection when working with a dedicated local contractor. We provide professional inspections to gather the necessary evidence for your case at no initial cost to you. Our goal is to ensure you have a comprehensive report that details every mat fracture and granule loss. This documentation is vital when you are figuring out how to appeal a denied roof insurance claim and need to prove the first adjuster was wrong.
Can a roofing contractor talk to my insurance adjuster for me?
Yes, a roofing contractor can and should speak with your adjuster regarding the technical aspects of the damage. While we don’t act as legal representatives, we serve as expert witnesses who understand the language adjusters use. We meet the adjuster on your roof to point out specific storm-related issues they might have missed. This professional-to-professional dialogue often clears up “confusion” over policy limits and local building codes without unnecessary conflict.
What happens if my appeal is denied a second time?
If your formal appeal is denied again, you have several options. You can file a consumer complaint with the Oklahoma Department of Insurance (OID) to request a regulatory review of the carrier’s decision. Alternatively, you might hire a Public Adjuster or an attorney who specializes in property insurance. These steps are a last resort, as most well-documented appeals are resolved through the re-inspection process we provide for our Tulsa neighbors.