


Table of Contents
- Understanding Roof Replacement Financing
- Average Cost of Roof Replacement and Budget Planning
- Roofing Payment Plans and Flexible Financing
- Home Improvement Loans for Roofing Projects
- How Roof Replacement Financing Affects Your Credit
- Insurance Claims and Financing Integration
- Steps to Apply for Roof Replacement Financing
- Conclusion
Last Updated: August 12, 2026
Understanding Roof Replacement Financing
Roof replacement financing spreads the cost of a new roof across manageable monthly payments rather than requiring full upfront payment. Most homeowners don’t have $8,000 to $15,000 in savings when a roof fails. Without financing, many delay repairs, accelerating water damage, structural deterioration, and safety risks. Rescue Roofing works with homeowners to explore flexible financing solutions that fit their budgets and allow you to address problems before minor leaks become major structural issues.
Several financing paths exist, each with different requirements, terms, and total costs. Understanding these options upfront helps you make an informed decision aligned with your financial situation and timeline.
Average Cost of Roof Replacement and Budget Planning
The cost of roof replacement varies significantly based on roof size, materials selected, regional labor rates, and installation complexity. A typical residential roof replacement requires an accurate estimate from a qualified contractor before committing to any financing option.
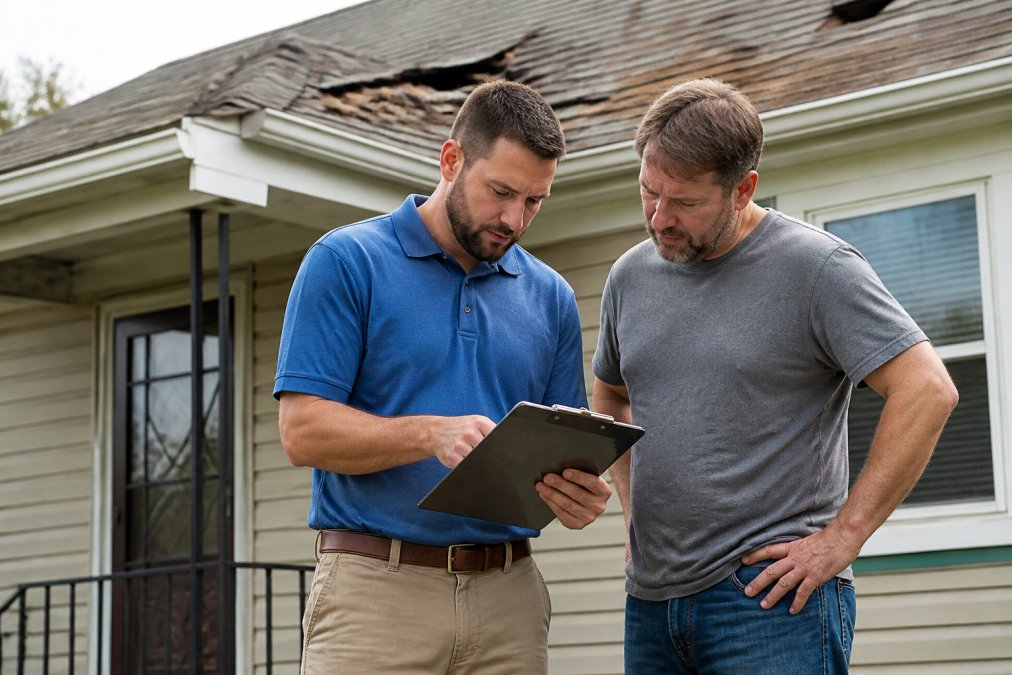
Your total project cost includes materials (shingles, underlayment, flashing), labor, disposal of old roofing, and any repairs discovered during installation. Rescue Roofing provides accurate aerial quotes using drone technology to assess your roof without surprises mid-project. A quality roof with proper installation lasts 20-30 years, making the annual cost relatively modest. Cheaper materials or rushed installation may require replacement sooner, increasing your total lifetime expenses.
Roofing Payment Plans and Flexible Financing
Many roofing contractors offer in-house payment plans allowing you to pay over time without a third-party lender. These arrangements typically feature fixed monthly payments spread across 12 to 60 months with simpler approval processes than traditional loans.
Same-as-cash financing programs charge zero interest if you pay the full balance within a promotional period, commonly 12 or 24 months. If you fail to pay by the deadline, interest accrues retroactively from the original purchase date, sometimes at higher rates. This option works well if you’re confident you can pay within the promotional window.
Installment payment plans spread costs evenly across your payment period with interest calculated upfront. You know your exact monthly payment and total interest cost from the start, removing pressure of a promotional deadline.
Home Improvement Loans for Roofing Projects
A home improvement loan is a personal loan specifically designated for property improvements, including roof replacement. These unsecured loans don’t require your home as collateral, meaning your property isn’t at risk if you default. However, unsecured status typically means higher interest rates than secured options.
Home improvement loans offer fixed interest rates and set repayment periods, usually ranging from 3 to 10 years. The application process involves a credit check and income verification. Your monthly payment remains constant throughout the loan term, making budgeting easy. The drawback is that unsecured personal loans typically carry higher interest rates than home equity options. Shopping rates across multiple lenders helps you find the best terms available.
How Roof Replacement Financing Affects Your Credit
Taking on roof replacement financing will impact your credit score, though the magnitude depends on the financing type, your existing credit profile, and how strategically you approach the application process.
Hard Inquiries and Initial Score Impact
When you apply for any credit product, the lender performs a hard inquiry on your credit report, typically lowering your score by 5 to 10 points. This impact is temporary; the inquiry falls off your report after 12 months and stops affecting your score after two years.
Multiple applications within a short window (typically 14 days) for the same type of credit count as a single inquiry under most credit scoring models. Shopping rates across three or four lenders for a personal loan doesn’t multiply the damage, it’s treated as one inquiry.
New Account and Credit Mix Effects
Once approved, the new financing account appears on your credit report, initially lowering your score by another 5 to 15 points. However, this new account increases your total available credit. If you don’t use that credit, your credit utilization ratio improves, which can offset the initial dip over time. Adding an installment loan to your credit mix can improve your score if you previously only had revolving credit like credit cards.
Payment History as the Dominant Factor
Payment history accounts for 35% of your credit score, the largest single factor. Making on-time payments on your roof financing for 12 to 24 months rebuilds and strengthens your credit significantly, often offsetting the initial inquiry and new account impacts entirely. Missing even one payment can drop your score 50 to 100 points, with late payments staying on your report for seven years.
Debt-to-Income Ratio Considerations
Roof financing increases your monthly debt obligations, affecting your debt-to-income ratio (DTI). Most lenders prefer a DTI below 43%. If you’re planning other major purchases within the next 12 to 24 months, a vehicle loan, mortgage refinance, or home equity line of credit, consider the timing of your roof financing carefully.
Strategic Timing and Application Approach
If your credit score is currently 700+, the impact of roof financing is relatively minor and recovers quickly with on-time payments. If your score is below 650, consider whether waiting 3 to 6 months to improve your score first would qualify you for better interest rates.
When applying, choose one financing path rather than applying to multiple lenders simultaneously for different product types. If you have an insurance claim pending, consider waiting for the claim decision before applying for financing. If the insurance payout covers most of the cost, you’ll need less financing, reducing your DTI impact.
Insurance Claims and Financing Integration
Many homeowners can offset roof replacement costs through insurance claims when damage results from storms, hail, wind, or other covered events. Integrating insurance claims with financing requires careful coordination and clear understanding of how claim payouts interact with your financing timeline.
Understanding Insurance Payout Types
Your homeowners insurance policy covers roof damage under one of two valuation methods: actual cash value (ACV) or replacement cost value (RCV).
Actual cash value pays the cost to replace your roof minus depreciation. If your roof is 15 years old and has a 25-year lifespan, the insurer depreciates it by 60%, paying only 40% of the replacement cost. For a $12,000 roof replacement, ACV might pay only $4,800 to $6,000.
Replacement cost value pays the full cost to replace your roof with materials of similar kind and quality, with no depreciation deduction. For the same $12,000 roof, RCV pays the full $12,000 (minus your deductible). Check your policy documents to confirm which valuation method your policy uses.
Deductibles and Out-of-Pocket Calculations
Your homeowners insurance policy includes a deductible, the amount you pay out of pocket before insurance coverage begins. Standard deductibles are $500, $1,000, or $2,500. When you file a roof claim, the insurance company pays (replacement cost or actual cash value) minus your deductible. If your roof replacement costs $12,000 and your deductible is $1,000, the insurance company pays $11,000 (assuming RCV). You’re responsible for the $1,000 deductible.
Timing Strategies: Finance First vs. Wait for Claim
Finance First Strategy: You obtain financing, start the roof replacement immediately, and apply insurance proceeds to pay down the loan balance when the claim is approved. Advantages: repairs begin immediately, preventing water damage; you maintain control over contractor selection and project timing; if the claim pays more than expected, you can pay down the loan faster and save on interest. Disadvantages: you carry the full loan balance initially, increasing your monthly payment and debt-to-income ratio; if the claim is denied or pays less than expected, you’re responsible for the full financed amount.
Wait for Claim Strategy: You file the insurance claim, wait for approval and payment, then use the proceeds to pay for the roof replacement. Advantages: you know exactly how much insurance will cover before committing to financing; you minimize or eliminate your financing need. Disadvantages: roof repairs are delayed, risking water damage and mold growth; if the claim is denied, you’ve delayed necessary repairs.
For most homeowners, the finance-first strategy is preferable when roof damage is severe or weather conditions are deteriorating. The cost of water damage and mold remediation often exceeds the interest cost of carrying the loan for a few weeks.
The Insurance Claim Process and Contractor Coordination
When you file a claim, your insurance company assigns an adjuster to assess the damage and prepare a damage estimate. A reputable roofing contractor can provide detailed damage documentation, prepare a comprehensive repair estimate, communicate directly with the adjuster, and challenge low estimates if necessary. If your contractor works directly with your insurance adjuster, the claim approval process moves faster and the payout is typically more accurate.
Applying Insurance Proceeds to Your Financing
Once your claim is approved and the insurance company issues payment, you can apply those funds directly to your lender to pay down the loan balance. This reduces your remaining balance and the total interest you’ll pay. For example, if you financed $12,000 at 8% interest over 5 years and the insurance company pays $8,000 after 4 weeks, your remaining balance drops to $4,000, and your monthly payment and total interest cost decrease accordingly.
Claim Denial and Contingency Planning
Insurance claims are sometimes denied or paid at lower amounts than expected. Common reasons include: the damage is deemed wear-and-tear rather than a covered event; the policy has exclusions for certain types of damage; or the homeowner failed to maintain the roof. Before filing a claim, review your policy exclusions and coverage limits to prevent surprises.
Steps to Apply for Roof Replacement Financing
Applying for roof replacement financing follows a straightforward process, though specific steps vary by financing type.
Step 1: Get a detailed roofing estimate. Obtain a comprehensive estimate from your contractor itemizing materials, labor, timeline, and total cost. Rescue Roofing provides detailed estimates using aerial assessment technology, ensuring accuracy.
Step 2: Determine your financing options. Research available financing paths, contractor payment plans, personal loans, home equity lines of credit, or same-as-cash programs. Compare interest rates, terms, and approval requirements.
Step 3: Gather required documentation. Most financing applications require proof of income (recent pay stubs or tax returns), identification, and basic financial information. Have these documents ready to accelerate the application process.
Step 4: Submit your application. Complete the financing application through your chosen lender or contractor. Be honest about your financial situation; lenders verify income and check credit reports.
Step 5: Review approval terms. Once approved, carefully review the loan agreement, interest rate, monthly payment, total interest cost, and repayment period. Ask your lender to clarify anything unclear.
Step 6: Schedule your project. After financing is approved and funds are available, coordinate with your contractor to schedule the roof replacement.
Step 7: Make your first payment. Your payment schedule begins either immediately or after a grace period. Set up automatic payments if available to avoid missed payments.
Conclusion
Roof replacement financing transforms an overwhelming expense into manageable monthly payments, allowing you to protect your home without financial strain. Whether you choose a contractor payment plan, personal loan, home equity line of credit, or same-as-cash program depends on your credit profile, timeline, and budget comfort level.
Rescue Roofing simplifies this process by providing accurate aerial quotes, assisting with insurance claims, and offering flexible financing partnerships. Contact Rescue Roofing today to discuss your roof replacement needs and explore financing options tailored to your situation. We’re available 24 hours to help you get started.
Frequently Asked Questions
What is the best way to finance a new roof?
The best financing method depends on your credit score, timeline, and equity position. Home equity lines of credit (HELOC) typically offer the lowest interest rates if you own your home outright or have substantial equity. Unsecured personal loans provide faster approval without collateral risk. Same-as-cash financing through roofing contractors works well for those who can pay within the promotional period. Compare APR, loan terms, and monthly payments across options before deciding which roof replacement financing approach fits your situation.
Can I pay monthly for a new roof?
Yes. Most roofing companies offer roofing payment plans either through in-house financing or partnerships with lending providers. These installment plans spread your roof replacement cost across 12 to 84 months, depending on the loan amount and your creditworthiness. Same-as-cash programs typically run 6 to 24 months with zero interest if paid in full by the end of the term. Monthly payments vary based on the total project cost, interest rate, and loan duration you select.
How does a roof replacement loan affect my credit score?
A hard credit inquiry when applying lowers your score by 5-10 points temporarily. Once approved, the new loan account slightly reduces your average account age. However, on-time monthly payments build positive payment history and lower your credit utilization ratio, which improves your score over time. The net impact is usually a short-term dip followed by gradual recovery within 6-12 months as you demonstrate reliable repayment.
Do roofing companies offer in-house payment plans?
Many roofing contractors, including local providers, partner with third-party lenders to offer flexible financing directly. Some larger companies manage their own financing programs. In-house payment plans through your roofing contractor simplify the process by consolidating your estimate, approval, and project timeline in one place. Ask your contractor whether they offer direct financing partnerships, same-as-cash programs, or referrals to lenders they work with regularly.
This article was written using GrandRanker