
Table of Contents
- What to Look for in a Reputable Roofing Contractor
- Roofing Contractor Red Flags to Avoid After a Storm
- Questions to Ask a Roofing Contractor Before Hiring
- How to Handle Roof Insurance Claims After Storm Damage
- Material Quality vs. Labor Quality: What Actually Matters
- Your Post-Repair Inspection Checklist
- Conclusion
- Frequently Asked Questions
Last Updated: October 1, 2026
What to Look for in a Reputable Roofing Contractor
After a storm hits, your roof is your first line of defense. Hiring the right roofing contractor protects your home, your wallet, and your peace of mind. This guide walks you through every step, from spotting red flags to handling your insurance claim.
The stakes are high. A bad hire can leave you with a leaking roof, an unpaid claim, and no one to call. A good one fixes the damage and handles the paperwork.
So what separates the two?
Verify Licensing and Insurance Coverage
A reputable contractor carries three things: a state license, general liability insurance, and workers compensation. Ask to see proof of all three before you sign anything.
Here is what each one covers:
- Contractor license: Proves the company meets state requirements.
- General liability insurance: Covers damage to your property during work.
- Workers compensation: Protects you if a worker gets hurt on your roof.
Never accept a verbal promise. Ask for certificates and call the insurer to confirm the policy is active.
Hiring an uninsured crew means you could pay out of pocket if someone falls or your siding gets damaged. Always confirm coverage before work begins.
Check for a Physical Business Location
A real company has a real address. Ask for the street address, not just a phone number or website.
Look it up. A physical office or warehouse signals a business that plans to stay put. Storm chasers work out of hotel rooms and move on within weeks.
Also check how long the company has operated in your area. Local roots matter when you need warranty work two years later.
Roofing Contractor Red Flags to Avoid After a Storm
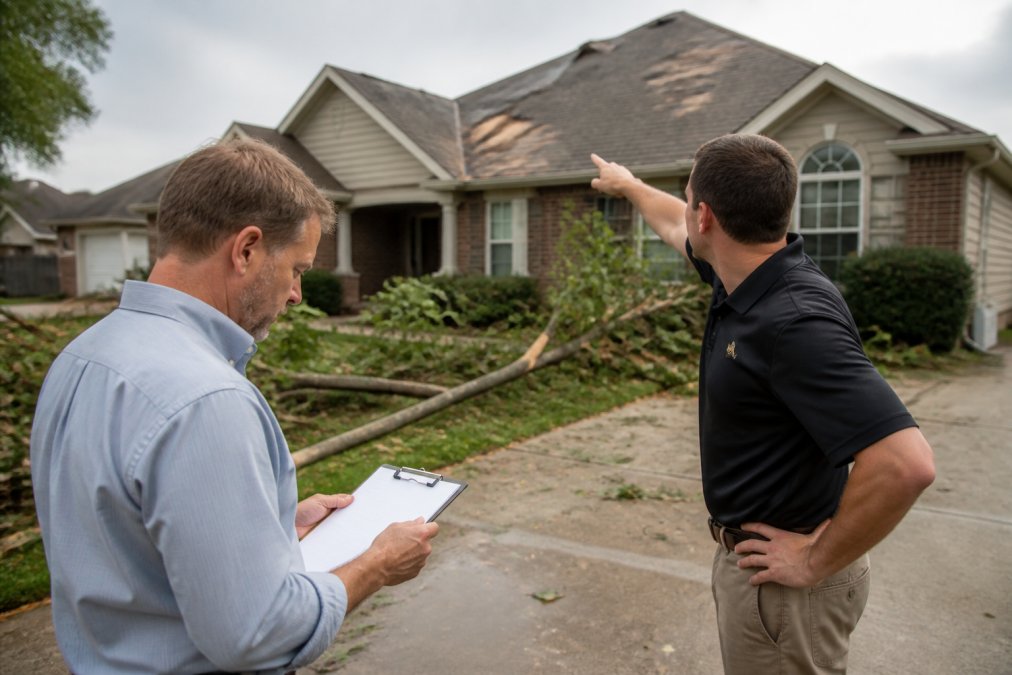
Storm damage brings out both good crews and bad actors. Knowing the warning signs saves you money and stress.
High-Pressure Tactics and Upfront Payment Demands
The biggest red flag is pressure. A legitimate roofing contractor never rushes you into a same-day decision.
Watch for these tactics:
- “We’re in the neighborhood and have leftover materials.”
- “Sign today or the price goes up tomorrow.”
- “We’ll waive your deductible.”
- Demands for full payment upfront.
A common mistake is paying a large deposit before any work starts. A fair schedule ties payments to milestones, not promises.
A deposit of a third or less is typical. If a contractor wants the full amount before ordering materials, walk away.
Questions to Ask a Roofing Contractor Before Hiring
The right questions reveal how a company operates. Ask these before you sign a contract:
- How long have you worked in this area?
- Can I see your license and insurance certificates?
- Will you provide a written estimate with a full project scope?
- Who handles the insurance claim, me or you?
- What does your workmanship warranty cover, and for how long?
- Will you use subcontractors or your own crew?
- Can you give me three local references from the past year?
What to Ask About Warranties and Timelines
Warranties come in two types. A manufacturer warranty covers the shingles themselves. A workmanship warranty covers the installation.
Both matter. Poor installation can void a manufacturer warranty, so a strong workmanship guarantee is your real safety net.
Ask how long each lasts and what voids them. Get the answer in writing.
Timelines matter too. Ask for a start date and a completion estimate. Weather can delay work, but a vague “sometime next month” is a warning sign.
How to Handle Roof Insurance Claims After Storm Damage
Filing a claim feels overwhelming, but the process follows a predictable sequence. Knowing what happens at each stage, and where contractors typically add value, keeps you from leaving money on the table.
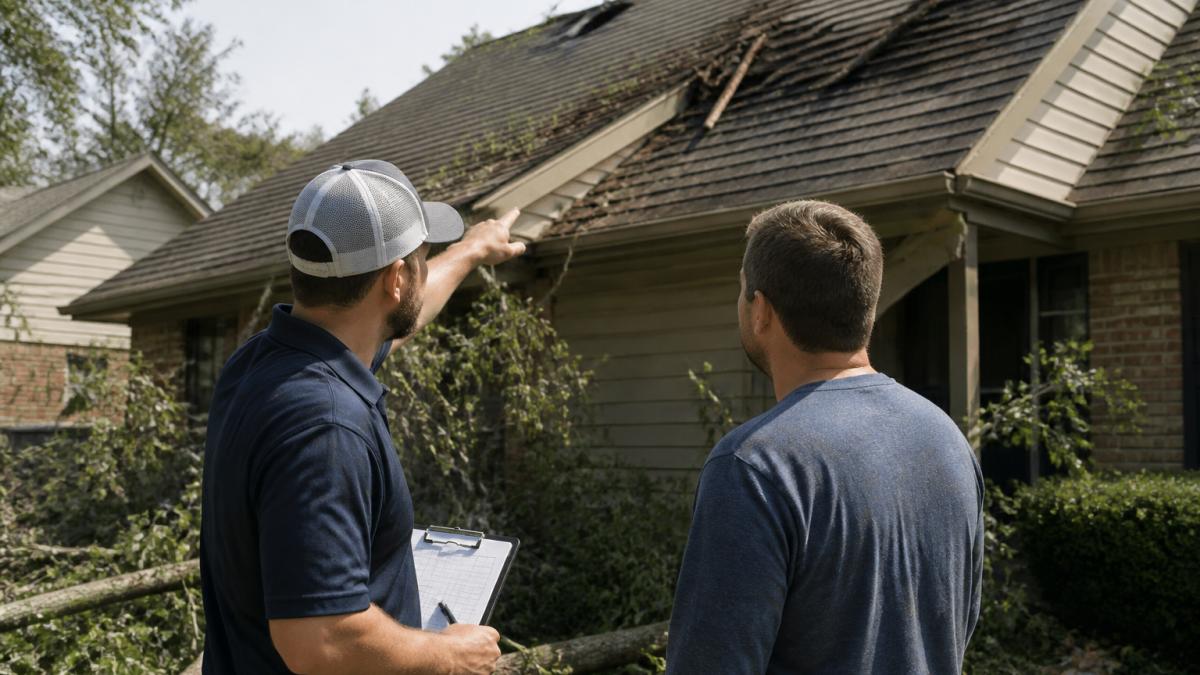
- Document the damage with dated photos, video, and written notes before anything is moved or repaired.
- Call your insurer and open a claim. Get the claim number and the name of the assigned adjuster.
- Meet the claims adjuster on site. Have your contractor present if possible.
- Review the adjuster’s estimate line by line, not just the bottom-line number.
- Hire your contractor, sign a scope of work, and start repairs.
- Track supplements and change orders as work uncovers hidden damage.
- Collect the final invoice, warranty documents, and lien waivers before final payment.
Your roofing contractor should work with the adjuster, not against them.
The Insurance Supplement Process Explained
- Rotten or delaminated decking hidden under shingles
- Damaged flashing, drip edge, or valley metal that only shows once tear-off begins
- Ice-and-water shield or underlayment that was not on the original scope
- Code-required upgrades, such as drip edge or ventilation changes triggered by the new roof
- Disposal fees, permits, and dumpster costs that vary by jurisdiction
Here is how the supplement process typically works:
- The contractor documents the additional damage with photos, measurements, and often a line-item estimate using industry-standard pricing software.
- The contractor submits the supplement to your insurer, usually with a cover letter referencing the claim number and the original adjuster estimate.
- The adjuster reviews the request and either approves, partially approves, or denies each line item.
- If approved, the insurer releases additional funds, often as a second check made out to you and your mortgage company if you have one.
- If denied, the contractor can request a re-inspection or you can invoke your policy’s appraisal clause.
Never let a contractor “eat” a supplement by quietly reducing the scope. If the decking is rotten, it needs to be replaced, not shingled over. Ask for the supplement paperwork in writing.
Two contract terms matter here. First, look for a clause stating the contractor will pursue supplements on your behalf at no additional cost. Second, check whether the contract is priced as a fixed bid or as a “scope of loss” agreement tied to the insurance estimate. Scope-of-loss contracts are standard in storm restoration and protect you if the adjuster’s number changes.
What to Do If the Claim Is Denied or Underpaid
Denials are not always final. Common reasons include a deductible that was not met, damage attributed to wear rather than the storm, or a policy exclusion for cosmetic damage.
If you believe the decision is wrong:
- Request the denial in writing with the specific policy language cited.
- Ask your contractor for a written rebuttal with photo evidence and code citations.
- Request a re-inspection with a different adjuster.
- File a complaint with your state insurance department.
- As a last resort, invoke the appraisal clause in your policy, which brings in a neutral umpire.
Material Quality vs. Labor Quality: What Actually Matters
Most homeowners focus on shingles. The real difference often comes down to labor.
Ask about these details:
- Shingle quality: Check the warranty rating and wind resistance.
- Underlayment: The layer beneath shingles that blocks water.
- Flashing: Metal pieces that seal joints and valleys.
- Ventilation: Proper airflow prevents moisture buildup.
- Fasteners: Nails and their placement affect wind resistance.
Labor quality often matters more than shingle brand. Ask how the crew installs, not just what they install.
Your Post-Repair Inspection Checklist
The job is not done when the crew leaves. Walk the property and confirm every item on this list:
- All old materials and debris removed
- Gutters cleared of nails and shingle scraps
- Flashing sealed around chimneys and vents
- Ridge and hip lines straight and secure
- No exposed nails on the roof surface
- Attic checked for leaks or daylight
- Final photos taken for your records
- Written warranty and receipts collected
Conclusion
Storm damage is stressful, and finding a trustworthy contractor makes it worse. Rescue Roofing helps homeowners in Tulsa and nearby areas with thorough inspections, accurate aerial quotes, and full support through the insurance claim process. Our team offers 24-hour availability and flexible financing options. Trust our experienced professionals to deliver reliable, high-quality roofing solutions tailored to your specific needs. Vetting the credentials of local service providers remains an essential step in finding reliable contractors who can restore your home to its original condition.
Frequently Asked Questions
What are the red flags of a dishonest roofing contractor?
Watch for contractors who demand full payment upfront, refuse to provide a written estimate, or pressure you to sign immediately. A contractor without a local address, verifiable license, or general liability insurance is a major risk. Storm chasers often appear after hail damage and disappear before warranty issues surface. If someone knocks on your door uninvited and claims your neighbor already signed, that is a high-pressure tactic, not a legitimate sales approach.
How can I verify a roofing contractor’s license and insurance?
Ask for the contractor’s license number and verify it with your state licensing board or local building department. Request a certificate of general liability insurance and workers compensation coverage, then call the insurance company directly to confirm the policy is active. A reputable roofing contractor will provide these documents without hesitation. If a contractor cannot produce proof of coverage, walk away. Uninsured workers on your property create liability for you as the homeowner.
How do I know if a roofing company is local and reputable?
Check for a physical business address, not just a phone number. Search the company name online and look for a verified Google Business Profile with reviews, a working website, and a history of completed projects in your area. Ask for local references from homeowners whose roofs the company replaced at least two years ago. A contractor with a real local presence will have a track record you can verify, including building permits filed under their name.
Should I get multiple quotes after storm damage?
Yes. Get at least three written estimates that break down the project scope, roofing materials, labor, and debris removal. Compare line items, not just totals. A suspiciously low bid often means shingle quality or labor will be cut. A written estimate should also clarify how the contractor handles insurance claims, whether they communicate with your claims adjuster, and what happens if hidden damage is found during the project. Ask each contractor the same questions to make an apples-to-apples comparison.